Aggressive SBA Debt Collection Is Happening in 2026: What Borrowers and Guarantors Must Know and Do Now
Aggressive SBA Debt Collection Is Happening in 2026. Learn what to expect and how Protect Law Group can help with SBA Debt Collection

Protect Law Group has the legal expertise to guide you through the SBA offer in compromise process and help successfully resolve your SBA loan problems.
Book a Consultation CallSBA Chief Maria Conteras-Sweet gave the commencement speech at Whittier College. Watch the entire speech.
If you are facing an SBA loan default, contact Protect Law Group today at www.sba-attorneys.com or 1-888-756-9969 to schedule your FREE initial consultation.

Millions of Dollars in SBA Debts Resolved via Offer in Compromise and Negotiated Repayment Agreements without our Clients filing for Bankruptcy or Facing Home Foreclosure
Millions of Dollars in Treasury Debts Defended Against via AWG Hearings, Treasury Offset Program Resolution, Cross-servicing Disputes, Private Collection Agency Representation, Compromise Offers and Negotiated Repayment Agreements
Our Attorneys are Authorized by the Agency Practice Act to Represent Federal Debtors Nationwide before the SBA, The SBA Office of Hearings and Appeals, the Treasury Department, and the Bureau of Fiscal Service.

Client personally guaranteed SBA 7(a) loan for $150,000. COVID-19 caused the business to fail, and the loan went into default with a balance of $133,000. Client initially hired a non-attorney consultant to negotiate an OIC. The SBA summarily rejected the ineligible OIC and the debt was referred to Treasury’s ureau of Fiscal Service for enforced collection in the debt amount of $195,000. We were hired to intervene and initiated discovery for SBA and Fiscal Service records. We were able to recall the case from Fiscal Service back to the SBA. We then negotiated a structured workout with favorable terms that saves the client approximately $198,000 over the agreed-upon workout term by waiving contractual and statutory administrative fees, collection costs, penalties, and interest.
Our firm successfully resolved an SBA 7a loan in the original amount of $364,000 for a New Jersey-based borrower. The client filed Chapter 7 bankruptcy but the mortgage on his real estate securing the loan remained in place. The available equity amounted to $263,470 and the deficiency equaled $317,886.
We gathered the pertinent documentation and prepared a comprehensive collateral analysis. We negotiated directly with the SBA, obtaining a full release of the mortgage for $80,000.
Client's small business obtained an SBA COVID EIDL for $301,000 pledging collateral by executing the Note, Unconditional Guarantee and Security Agreement. The business defaulted on the loan and the SBA CESC called the Note and Guarantee, accelerated the principal balance due, accrued interest and retracted the 30-year term schedule.
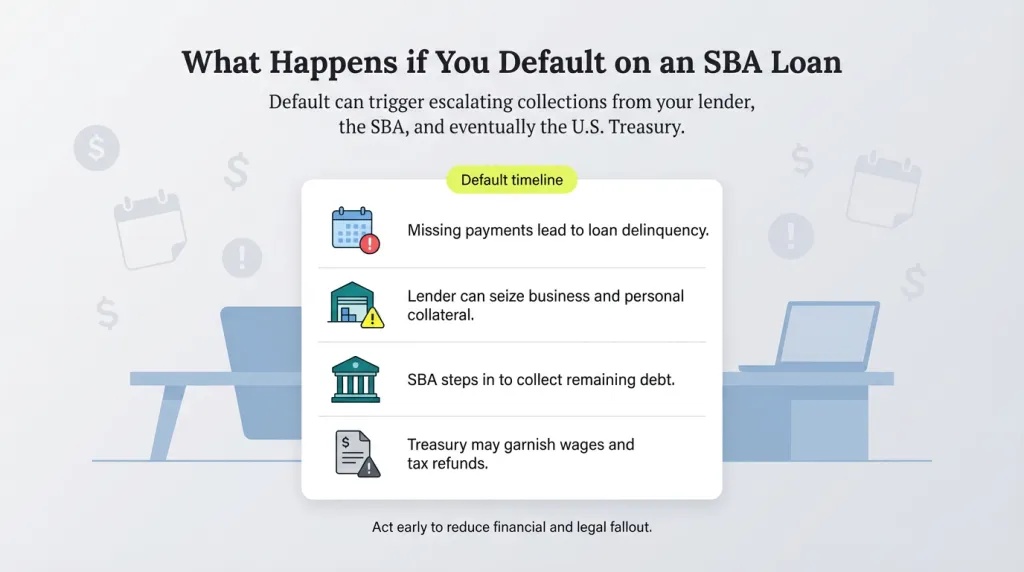
The loan was transferred to the Treasury's Bureau of Fiscal Service which resulted in the statutory addition of $90,000+ in administrative fees, costs, penalties and interest with the total debt now at $391.000+. Treasury also initiated a Treasury Offset Program (TOP) levy against the client's federal contractor payments for the full amount each month - intercepting all of its revenue and pushing the business to the brink of bankruptcy.
The Firm was hired to investigate and find an alternate solution to the bankruptcy option. After submitting formal production requests for all government records, it was discovered that the SBA failed to send the required Official 60-Day Pre-Referral Notice to the borrower and guarantor prior to referring the debt to Treasury. This procedural due process violation served as the basis to submit a Cross-Servicing Dispute to recall the debt from Treasury back to the SBA and to negotiate a reinstatement of the original 30-year maturity date, a modified workout, cessation of the TOP levy against the federal contractor payments and removal of the $90,000+ Treasury-based collection fees, interest and penalties.


