Aggressive SBA Debt Collection Is Happening in 2026: What Borrowers and Guarantors Must Know and Do Now
Aggressive SBA Debt Collection Is Happening in 2026. Learn what to expect and how Protect Law Group can help with SBA Debt Collection

Explore why business owners seek an SBA offer in compromise and review the debt collection concerns discussed in this article.
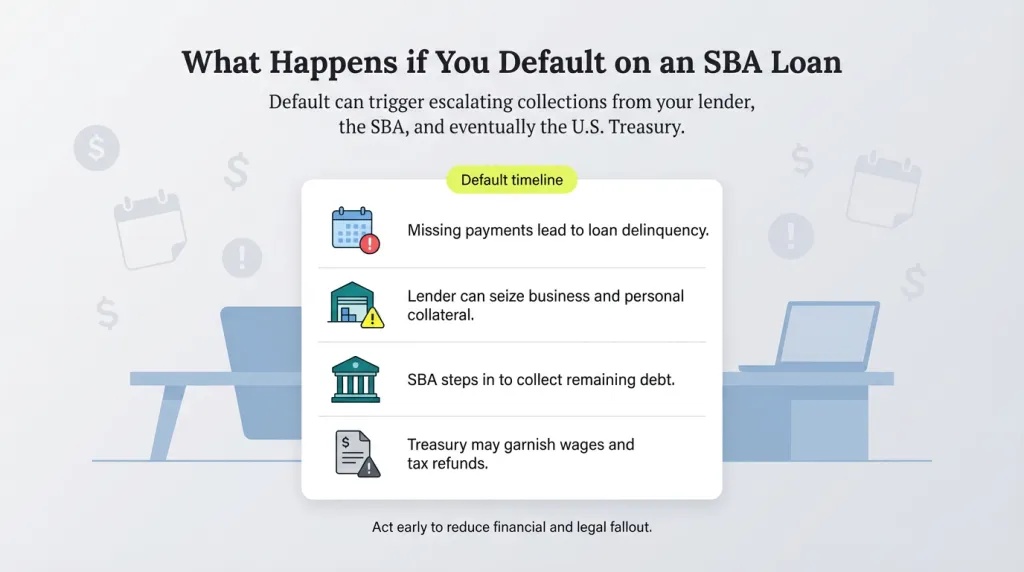
Book a Consultation CallThe federal Small Business Administration does a lot of important work for the nation's economy, advocating for and educating the founders and operators of hundreds of thousands of small companies. One of the SBA's most popular service offers is its loan program, an option that can see borrowers gaining access to credit at favorable terms where they might otherwise have been denied. While the program itself is therefore fairly generous, an SBA loan default is typically a serious matter, as the agency has a variety of ways of recouping money that might normally be drained from its coffers.
Borrowers who have failed to keep up with payments typically receive ample notice before things become more serious, however. By the time an SBA demand letter arrives in a borrower's hands, it is best to have already begun making arrangements to satisfy the obligation. Avoiding an SBA loan foreclosure or other harsh measure should almost always be a high priority, and it can be much easier to do so when skilled assistance is available.
The fact is that many borrowers have options beyond finding the money needed to fully satisfy a loan. While it can be difficult for laypersons to extract concessions from SBA negotiators and agents, those who are informed about the law and the relevant norms often have much greater success.
What this often means in practice is that it can be a good idea to get in touch with an attorney once it becomes apparent that trouble is in the making. One commonly appealing option is for a business owner to settle a loan with lessened requirements compared to the original terms, a victory that can allow a company to continue instead of effectively being forced into bankruptcy.
Obtaining such an SBA Offer in Compromise can be challenging, but the results are frequently worth the effort that is put in. An acceptable offer can see a company and its owner freed from the threat of foreclosure or the confiscation of refunds under the Tax Offset Program, making it much easier to recover from financial difficulties. For these reasons and others, actively seeking out the best possible resolution is typically far superior to allowing things to run their course.

Millions of Dollars in SBA Debts Resolved via Offer in Compromise and Negotiated Repayment Agreements without our Clients filing for Bankruptcy or Facing Home Foreclosure
Millions of Dollars in Treasury Debts Defended Against via AWG Hearings, Treasury Offset Program Resolution, Cross-servicing Disputes, Private Collection Agency Representation, Compromise Offers and Negotiated Repayment Agreements
Our Attorneys are Authorized by the Agency Practice Act to Represent Federal Debtors Nationwide before the SBA, The SBA Office of Hearings and Appeals, the Treasury Department, and the Bureau of Fiscal Service.

Client personally guaranteed an SBA 7(a) loan for $100,000 from the lender. The SBA loan went into early default in 2006 less than 12 months from disbursement. The SBA paid the 7(a) guaranty monies to the lender and subsequently acquired the deficiency balance of about $96,000, including the right to collect against the guarantor. However, the SBA sent the Official 60-Day Due Process Notice to the Client's defunct business address instead of his personal residence, which he never received. As a result, the debt was transferred to Treasury's Bureau of Fiscal Service where substantial collection fees were assessed, including accrued interest per the promissory note. Treasury eventually referred the debt to a Private Collection Agency (PCA) - Pioneer Credit Recovery, Inc. Pioneer sent a demand letter claiming a debt balance of almost $310,000 - a shocking 223% increase from the original loan amount assigned to the SBA. Client's social security disability benefits were seized through the Treasury Offset Program (TOP). Client hired the Firm to represent him as the debt continued to snowball despite seizure of his social security benefits and federal tax refunds as the involuntary payments were first applied to Treasury's collection fees, then to accrued interest with minimal allocation to the SBA principal balance.
We initially submitted a Cross-Servicing Dispute (CSD) challenging the referral of the debt to Treasury based on the defective notice sent to the defunct business address. Despite overwhelming evidence proving a violation of the Client's Due Process rights, the SBA still rejected the CSD. As a result, an Appeals Petition was filed with the SBA Office of Hearings & Appeals (OHA) Court challenging the SBA decision and its certification the debt was legally enforceable in the amount claimed. After several months of litigation before the SBA OHA Court, our Firm Attorney successfully negotiated an Offer in Compromise (OIC) Term Workout with the SBA Supervising Trial Attorney for $82,000 spread over a term of 74 months at a significantly reduced interest rate saving the Client an estimated $241,000 in Treasury collection fees, accrued interest (contract interest rate and Current Value of Funds Rate (CVFR)), and the PCA contingency fee.
Client’s small business obtained an SBA 7(a) loan for $750,000. She and her husband signed personal guarantees exposing all of their non-exempt income and assets. With just 18 months left on the maturity date and payment on the remaining balance, the Great Recession of 2008 hit, which ultimately caused the business to fail and default on the loan terms. The 7(a) lender accelerated and sent a demand for full payment of the remaining loan balance. The SBA lender’s note allowed for a default interest rate of about 7% per year. In response to the lender's aggressive collection action, Client's husband filed for Chapter 7 bankruptcy in an attempt to protect against their personal assets. However, his bankruptcy discharge did not relieve the Client's personal guarantee liability for the SBA debt. The SBA lender opted to pursue the SBA 7(a) Guaranty and subsequently assigned the loan and the right to enforce collection against the Client to the SBA. The Client then received the SBA Official 60-Day Notice. After conducting a Case Evaluation with her, she then hired the Firm to respond and negotiate on her behalf with just 34 days left before the impending referral to Treasury. The Client wanted to dispute the SBA’s alleged debt balance as stated in the 60-Day Notice by claiming the 7(a) lender failed to liquidate business collateral in a commercially reasonable manner - which if done properly - proceeds would have paid back the entire debt balance. However, due to time constraints, waivers contained in the SBA loan instruments, including the fact the Client was not able to inspect the SBA's records for investigation purposes before the remaining deadline, Client agreed to submit a Structured Workout for the alleged balance in response to the Official 60-Day Notice as she was not eligible for an Offer in Compromise (OIC) because of equity in non-exempt income and assets. After back and forth negotiations, the SBA Loan Specialist approved the Workout proposal, reducing the Client's purported liability by nearly $142,142.27 in accrued interest, and statutory collection fees. Without the Firm's intervention and subsequent approval of the Workout proposal, the Client's debt amount (with accrued interest, Treasury's statutory collection fee and Treasury's interest based on the Current Value of Funds Rate (CVFR) would have been nearly $291,030.
Client personally guaranteed an SBA 7(a) loan to help with a relative’s new business venture. After the business failed, Treasury was able to secure a recurring Treasury Offset Program (TOP) levy against his monthly Social Security Benefits based on the claim that he owed over $1.2 million dollars. We initially submitted a Cross-Servicing Dispute, but then, prepared and filed an Appeals Petition with the SBA Office of Hearings and Appeals (SBA OHA). As a result of our efforts, we were able to convince the SBA to not only terminate the claimed debt of $1.2 million dollars against our client (without him having to file bankruptcy) but also refund the past recurring amounts that were offset from his Social Security Benefits in connection with the TOP levy.


