If you Owe more than $30,000 contact us for a case evaluation at 888-756-9969
contact us for a free case evaluation at 888-756-9969
Call us 888-756-9969

SBA Debt Resolution Attorneys

We Provide Nationwide Representation of Small Business Owners, Personal Guarantors, and Federal Debtors with More Than $30,000 in Debt before the SBA and Treasury Department's Bureau of Fiscal Service

No Affiliation or Endorsement by any Federal Agency

Book a Consultation Call

SBA Debt Attorneys

Owe more than $30,000? If yes, we can provide you realistic solutions to SBA loan problems and US Treasury Debt Collection Tactics.

Would you like to know more about your SBA loan problem?

The SBA Attorneys in our office want to help you resolve your SBA debt situation. No matter how difficult your circumstances may seem, the right SBA debt attorneys can assist you.

We understand that you may have questions regarding a wide range of federal agency matters, including how to respond to an SBA demand letter, what SBA loan foreclosure actually entails, and what is a Treasury Offset Program levy.

Our SBA Attorneys can explain all of these topics and more. We urge you to review our disclaimer and blog to learn more about subjects that may be confusing to you and to contact us right away if you have specific questions relating to your unique circumstances.

We look forward to helping you during this difficult and stressful period of your life.

Why Hire Us to Help You with Your Treasury or SBA Debt Problems?

construction accident injury lawyer

Millions of Dollars in SBA Debts Resolved via Offer in Compromise and Negotiated Repayment Agreements without our Clients filing for Bankruptcy or Facing Home Foreclosure

slip and fall attorney

Millions of Dollars in Treasury Debts Defended Against via AWG Hearings, Treasury Offset Program Resolution, Cross-servicing Disputes, Private Collection Agency Representation, Compromise Offers and Negotiated Repayment Agreements

truck accident injury attorney

Our Attorneys are Authorized by the Agency Practice Act to Represent Federal Debtors Nationwide before the SBA, The SBA Office of Hearings and Appeals, the Treasury Department, and the Bureau of Fiscal Service.

$212,000 SBA 7(a) LOAN – PERSONAL GUARANTY LIABILITY | NEGOTIATED 24% SETTLEMENT

$212,000 SBA 7(a) LOAN – PERSONAL GUARANTY LIABILITY | NEGOTIATED 24% SETTLEMENT

Our firm successfully resolved an SBA 7(a) loan default in the amount of $212,000 on behalf of an individual guarantor. The borrower’s business experienced a significant downturn in revenue and was unable to sustain operations, ultimately leading to closure and a remaining personal guaranty obligation.

After conducting a thorough financial review and preparing a comprehensive SBA Offer in Compromise (SBA OIC) submission, we negotiated directly with the SBA and lender to achieve a settlement of $50,000—approximately 24% of the outstanding balance. This favorable resolution released the guarantor from further personal liability and provided the opportunity to move forward free from the burden of enforced collection.

‍

$150,000 SBA 7A LOAN - SBA OIC CASH SETTLEMENT

$150,000 SBA 7A LOAN - SBA OIC CASH SETTLEMENT

Client personally guaranteed SBA 7(a) loan balance of over $150,000.  Business failed and eventually shut down.  SBA then pursued client for the balance.  We intervened and was able to present an SBA OIC that was accepted for $30,000.

$1,200,000 SBA 7A LOAN - SBA OHA LITIGATION

$1,200,000 SBA 7A LOAN - SBA OHA LITIGATION

Client personally guaranteed an SBA 7(a) loan to help with a relative’s new business venture.  After the business failed, Treasury was able to secure a recurring Treasury Offset Program (TOP) levy against his monthly Social Security Benefits based on the claim that he owed over $1.2 million dollars. We initially submitted a Cross-Servicing Dispute, but then, prepared and filed an Appeals Petition with the SBA Office of Hearings and Appeals (SBA OHA).  As a result of our efforts, we were able to convince the SBA to not only terminate the claimed debt of $1.2 million dollars against our client (without him having to file bankruptcy) but also refund the past recurring amounts that were offset from his Social Security Benefits in connection with the TOP levy.

Read more Case Results
SBA Debt Default FAQs
Does The Compromise With One Or More Obligor Release The Liability Of The Remaining Obligors?

A compromise with one or more Obligors does not release the continuing liability of any remaining Obligors. Each entity or individual responsible for the debt must develop its/his/her own SBA OIC.

What are the criteria for a business to file under Subchapter V?

To be eligible for this option, a debtor must meet the following criteria:

  • Engaged in commercial activity
  • Total debts must be less than $2,725,725 (both secured and unsecured)
  • At least half of the debts must be due to business activity
  • The principal activity is not a single-asset real estate operation

The CARES Act further expanded the eligibility for businesses to qualify under this bankruptcy path.

This legislation increases the eligibility pool to also include companies with up to $7,500,000 in debt (both secured and unsecured) to reorganize under Subchapter V. This is a significant increase from the otherwise limit of $2,725,625.

‍

Can an individual use Subchapter V?

Yes, as long as you meet the criteria above individuals may avail themselves of Subchapter V.

What Occurs When An SBA Loan Goes Into Default?

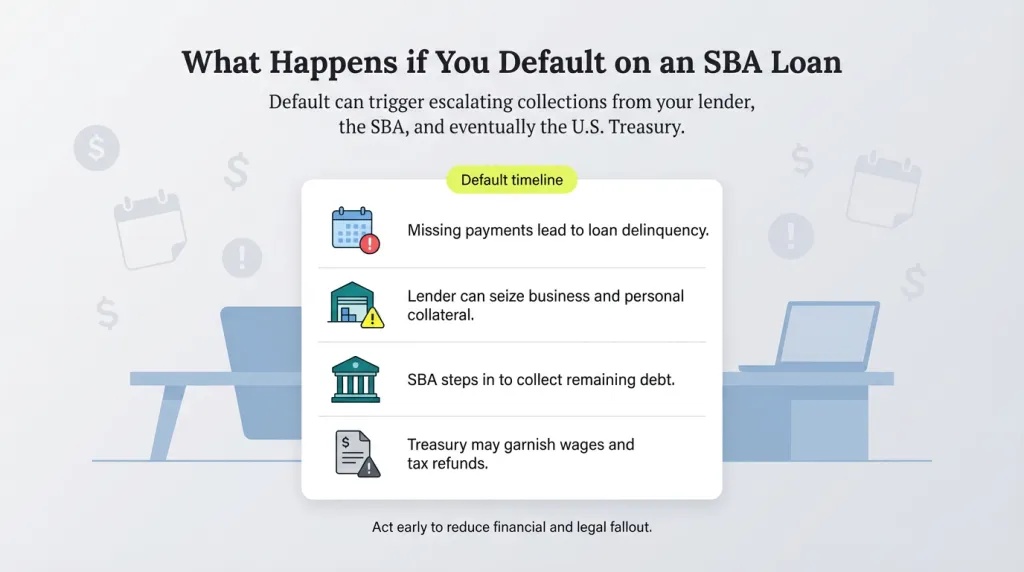
When you fail to make payments on your SBA loan, the bank or CDC will start contacting you asking for payment. Eventually, if non-payment continues, and you fail to cure the “default”, the bank or CDC may seek to collect on its collateral. This could include monies contained in an account housed at the same bank, your account receivables, your business equipment, real estate, even your home if you used a mortgage beyond the homestead exemption limits. You can expect that the bank or CDC will aggressively seize pledged collateral because the SBA requires the lender or CDC to take all appropriate steps to collect as much of the debt as it can before tendering a claim to the SBA for the balance. And if the United States Department of Treasury receives your account, then you can expect more aggressive collection action, and possibly, full-fledged litigation.

When is a Charge Off Justified?

A charge off is justified when the SBA has complied with all requirements of collection and liquidation and further collection of any substantial portion of the debt is doubtful. The determination to justify a charge off may be based on one or more of the following:a) All efforts must have been exhausted in cost-effective recovery from:1. Voluntary payments from the borrower;2. Liquidation of collateral;3. Compromise with obligor leaving only a deficiency balance; and4. Consideration has been given to any legal remedies available so that no further reasonable expectation of recovery remains.b) Estimated costs of future collection exceed any anticipated recovery;c) Obligor cannot be located or is judgment proof;d) The Lender/SBA’s rights have expired (e.g., statute of limitations, restrictions of State law, SBA policy);e) Debt is legally without merit;f) Adjudication of a Chapter 7 Bankruptcy as a no asset case, or completion of Chap 11/13 case;g) The inability of the Lender to effect further worthwhile recovery.

Read more sba debt FAqs
Read more sba debt articles