Aggressive SBA Debt Collection Is Happening in 2026: What Borrowers and Guarantors Must Know and Do Now
Aggressive SBA Debt Collection Is Happening in 2026. Learn what to expect and how Protect Law Group can help with SBA Debt Collection

Explore the pros and cons of SBA loan default versus Chapter 7 bankruptcy. Discover which path aligns with your financial goals.
Book a Consultation CallFor small business owners facing financial distress, the decision between addressing an SBA loan default and filing for Chapter 7 bankruptcy can feel daunting. Both options come with serious implications, affecting your financial future, personal assets, and business viability. Understanding the nuances of each path is crucial for making an informed decision that aligns with your goals and circumstances.
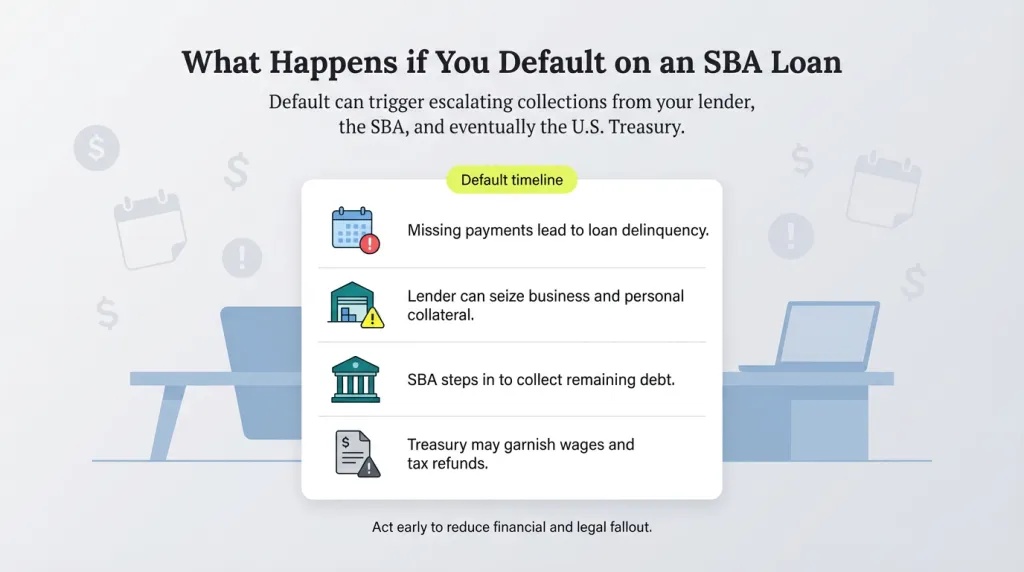
When a business defaults on an SBA loan, it means that the borrower has failed to make the required payments according to the loan agreement. This can initiate a series of actions by the lender, including potential legal proceedings to recover the outstanding loan balance. The repercussions of an SBA loan default extend beyond just the business, often impacting personal guarantors who may be liable for the debt.
Pros:
Cons:
Chapter 7 bankruptcy, often referred to as "liquidation bankruptcy," involves the sale of a debtor's non-exempt assets to repay creditors. This option is typically considered when a business cannot feasibly repay its debts and has no viable path to restructuring.
Pros:
Cons:
Choosing between addressing an SBA loan default and filing for Chapter 7 bankruptcy requires a thorough evaluation of your financial situation, goals, and the specific circumstances surrounding your business. Here are some critical factors to consider:
When comparing SBA loan default and Chapter 7 bankruptcy, it's essential to understand how each option aligns with your specific needs and circumstances. Here’s a side-by-side look at some critical aspects:
| Aspect | SBA Loan Default | Chapter 7 Bankruptcy |
|---|---|---|
| Debt Relief Approach | Negotiated settlement via OIC | Legal discharge through asset liquidation |
| Impact on Business | Requires business closure for OIC | Typically results in business closure |
| Credit Implications | Negative impact, possible settlement | Significant impact, bankruptcy noted for 10 years |
| Asset Requirements | Liquidation of business assets required | Liquidation of non-exempt assets |
| Legal Proceedings | Negotiation-focused, can be lengthy | Court-supervised, structured process |
| Outcome Certainty | Outcome varies based on negotiations | Predictable outcome, debt discharge |
| Protection from Creditors | Limited, subject to negotiation terms | Automatic stay provides protection |
Choosing the right path between SBA loan default and Chapter 7 bankruptcy depends on a variety of personal and business factors. Both pathways offer distinct forms of relief but come with their own sets of challenges and requirements. The key is to evaluate your unique situation, including your financial health, business prospects, and personal priorities.
Engaging with a law firm that specializes in federal debt defense and bankruptcy can provide critical insights and strategies tailored to your situation. Protect Law Group, for example, offers expertise in both SBA debt negotiation and bankruptcy proceedings, helping you navigate these complex waters with confidence.
Ultimately, the choice between addressing an SBA loan default and filing for Chapter 7 bankruptcy should be based on a comprehensive understanding of each option's implications. By evaluating your financial circumstances, assessing potential outcomes, and seeking expert advice, you can make a decision that aligns with your long-term financial goals and personal well-being.
If you find yourself at this financial crossroads, it’s important to act strategically. A free case evaluation with Protect Law Group can help clarify your options, understand your rights, and determine the most viable path forward. Contact us at 888-756-9969 to discuss how we can assist you in navigating SBA loan defaults, Chapter 7 bankruptcy, or exploring other debt relief options for small businesses. Your journey to financial recovery starts with informed decisions and expert guidance.
This article is provided for informational purposes only and does not constitute legal advice. Consult a qualified SBA-Attorney for advice regarding your individual situation.
Facing an SBA loan default or considering Chapter 7 bankruptcy? Understand your options and make an informed decision with expert guidance. Contact Protect Law Group today for a free case evaluation to discuss the strategic path forward tailored to your financial situation.
An SBA loan default occurs when a borrower fails to make the required payments as per the loan agreement, prompting potential legal actions by the lender.
Chapter 7 bankruptcy allows for the liquidation of non-exempt assets to discharge debts, but it may involve losing significant personal and business assets.
Yes, alternatives exist such as SBA Offer in Compromise or loan deferment, which can potentially minimize financial damage without filing for bankruptcy.
Personal guarantors may become liable for the unpaid balance of the loan, resulting in personal financial risk and potential asset seizures.
Protect Law Group offers strategic guidance and representation in navigating SBA debt defenses and exploring bankruptcy alternatives to protect your assets and business future.

Millions of Dollars in SBA Debts Resolved via Offer in Compromise and Negotiated Repayment Agreements without our Clients filing for Bankruptcy or Facing Home Foreclosure
Millions of Dollars in Treasury Debts Defended Against via AWG Hearings, Treasury Offset Program Resolution, Cross-servicing Disputes, Private Collection Agency Representation, Compromise Offers and Negotiated Repayment Agreements
Our Attorneys are Authorized by the Agency Practice Act to Represent Federal Debtors Nationwide before the SBA, The SBA Office of Hearings and Appeals, the Treasury Department, and the Bureau of Fiscal Service.

Small business and guarantors obtained an SBA COVID-EIDL loan for $1,000,000. Clients defaulted causing SBA to charge-off the loan, accelerate the balance and refer the debt to Treasury's Bureau of Fiscal Service for collection. Treasury added nearly $500,000 in collection fees totaling $1,500,000. Clients were served with the SBA's Official 60-Day Notice and exercised the Repayment option by applying for the SBA’s Hardship Accommodation Plan. However, their application was summarily rejected by the SBA without providing any meaningful reasons. Clients hired the Firm to represent them against the SBA, Treasury and a Private Collection Agency. After securing government records through discovery, we filed an Appeals Petition with the SBA Office of Hearings & Appeals (OHA) court challenging the SBA's referral of the debt to Treasury. During litigation and before the OHA court issued a final Decision and Order, the Firm successfully negotiated a reinstatement and recall of the loan back to the SBA, a modification of the original repayment terms, termination of Treasury's enforced collection and removal of the statutory collection fees.
The client personally guaranteed an SBA 7(a) loan for $150,000. His business revenue decreased significantly causing default and an accelerated balance of $143,000. The client received the SBA's Official 60-day notice with the debt scheduled for referral to the Treasury’s Bureau of Fiscal Service for aggressive collection in less than 26 days. We were hired to represent him, respond to the SBA's Official 60-day notice, and prevent enforced collection by the Treasury and the Department of Justice. We successfully negotiated a structured workout with an extended maturity date that included a reduction of the 14% interest rate and removal of substantial collection fees (30% of the loan balance), effectively saving the client over $242,000.
Clients executed several trust deeds pledging seven (7) real estate properties and unconditional personal guarantees for an SBA 7(a) loan from the participating lender. The clients' small business failed and eventually defaulted on repayment of the loan exposing all collateral pledged by the clients. The SBA subsequently acquired the loan balance from the lender, including the right to liquidate and collect all pledged collateral pursuant to the trust deed instruments.
The Firm was hired to negotiate separate release of lien proposals for all 7 real estate properties. In preparation for the work assignment, the Firm Attorneys initiated discovery to secure records from the SBA and Treasury's Bureau of Fiscal Service. After reviewing the records and understanding the interplay between the lender and the SBA, the attorneys then prepared, submitted and negotiated the release of lien (ROL) for each of the 7 real estate properties for consideration.
After submitting the proposals, the assigned SBA Loan Specialists approved each ROL package - significantly reducing the total SBA debt claimed.


