On this page
Anytime you default on a loan, there are consequences, most of which are not the most favorable. Protect Law Group helps small business owners when they are unable to pay on their SBA loan and it enters into default. Below, we'll take a look at some of the consequences of an SBA loan default. Call our SBA lawyers for a free consultation today!
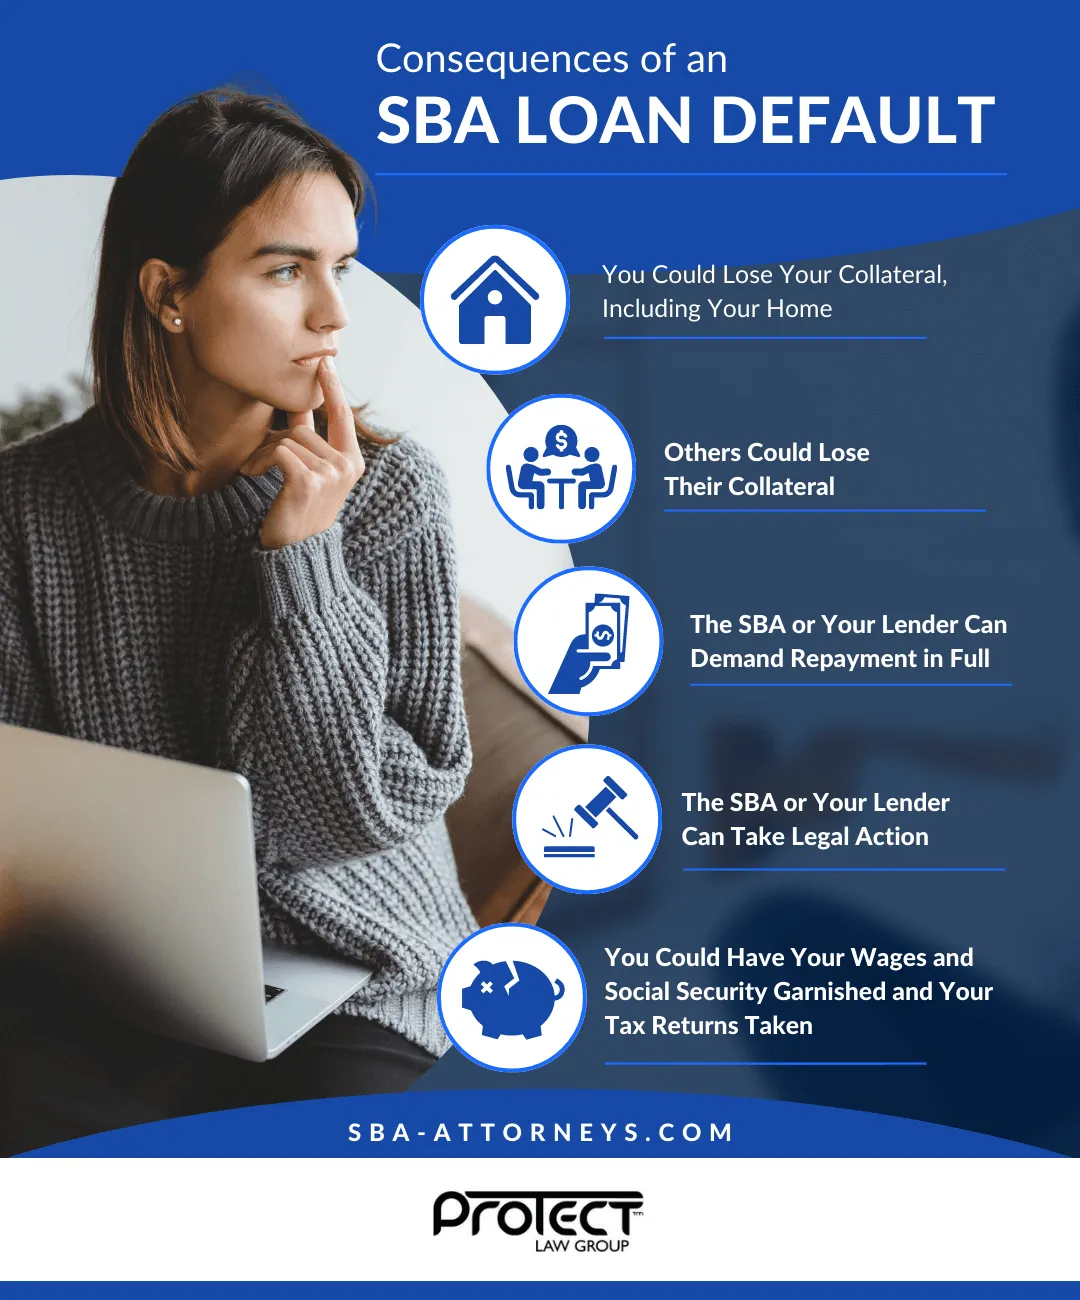
You Could Lose Your Collateral
If you used collateral as any part of security for your SBA loan (this can be your home, car, or other business assets), the lender could seize these assets in order to sell and hope to recoup the money they lent to you.
Others Could Lose Their Collateral
If anyone else co-signed on your SBA loan, then their assets could also be at risk. The lender has the right to take assets in order to recoup their losses from anyone who guaranteed the loan.
The SBA or Your Lender Can Demand Repayment in Full
The lender can take their case to the SBA and ask them to issue a demand letter, which is basically a legal and a formal demand for repayment of your defaulted SBA Loan.
The SBA or Your Lender Can Take Legal Action
The lender can take you to court and receive a judgment against you, giving them the right to take money from your bank account. They can also garnish your wages and your social security funds. In sum, they will take a fine tooth comb and analyze any and all business and personal assets you have in order to receive some compensation.
PARTNER WITH PROTECT LAW GROUP TODAY
Protect Law Group offers the top-rated SBA attorneys who will fight for you when your SBA loan enters default. With our years of experience and knowledge of the law, we are able to help our clients walk away with just settlements. Call our SBA debt resolution attorneys for a free consultation today!
Published by Protect Law Group. This material provides general information. Contact the firm for advice about your circumstances.
Schedule a Case Evaluation