SBA Loan Acceleration: Understanding Notice and Your Legal Options
Explore SBA loan acceleration's impact. Learn triggers, implications, and legal options to defend against accelerated payment demands.

We Provide Nationwide Representation of Small Business Owners, Personal Guarantors, and Federal Debtors with More Than $30,000 in Debt before the SBA and Treasury Department's Bureau of Fiscal Service
No Affiliation or Endorsement by any Federal Agency

Millions of Dollars in SBA Debts Resolved via Offer in Compromise and Negotiated Repayment Agreements without our Clients filing for Bankruptcy or Facing Home Foreclosure
Millions of Dollars in Treasury Debts Defended Against via AWG Hearings, Treasury Offset Program Resolution, Cross-servicing Disputes, Private Collection Agency Representation, Compromise Offers and Negotiated Repayment Agreements
Our Attorneys are Authorized by the Agency Practice Act to Represent Federal Debtors Nationwide before the SBA, The SBA Office of Hearings and Appeals, the Treasury Department, and the Bureau of Fiscal Service.

Client personally guaranteed an SBA 7(a) loan to help with a relative’s new business venture. After the business failed, Treasury was able to secure a recurring Treasury Offset Program (TOP) levy against his monthly Social Security Benefits based on the claim that he owed over $1.2 million dollars. We initially submitted a Cross-Servicing Dispute, but then, prepared and filed an Appeals Petition with the SBA Office of Hearings and Appeals (SBA OHA). As a result of our efforts, we were able to convince the SBA to not only terminate the claimed debt of $1.2 million dollars against our client (without him having to file bankruptcy) but also refund the past recurring amounts that were offset from his Social Security Benefits in connection with the TOP levy.
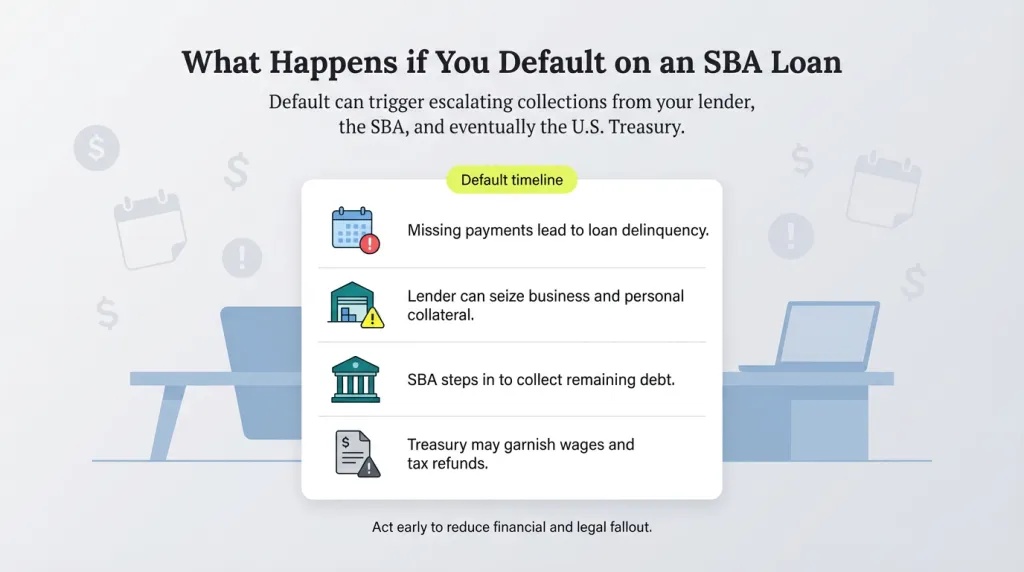
Client’s small business obtained an SBA 7(a) loan for $750,000. She and her husband signed personal guarantees exposing all of their non-exempt income and assets. With just 18 months left on the maturity date and payment on the remaining balance, the Great Recession of 2008 hit, which ultimately caused the business to fail and default on the loan terms. The 7(a) lender accelerated and sent a demand for full payment of the remaining loan balance. The SBA lender’s note allowed for a default interest rate of about 7% per year. In response to the lender's aggressive collection action, Client's husband filed for Chapter 7 bankruptcy in an attempt to protect against their personal assets. However, his bankruptcy discharge did not relieve the Client's personal guarantee liability for the SBA debt. The SBA lender opted to pursue the SBA 7(a) Guaranty and subsequently assigned the loan and the right to enforce collection against the Client to the SBA. The Client then received the SBA Official 60-Day Notice. After conducting a Case Evaluation with her, she then hired the Firm to respond and negotiate on her behalf with just 34 days left before the impending referral to Treasury. The Client wanted to dispute the SBA’s alleged debt balance as stated in the 60-Day Notice by claiming the 7(a) lender failed to liquidate business collateral in a commercially reasonable manner - which if done properly - proceeds would have paid back the entire debt balance. However, due to time constraints, waivers contained in the SBA loan instruments, including the fact the Client was not able to inspect the SBA's records for investigation purposes before the remaining deadline, Client agreed to submit a Structured Workout for the alleged balance in response to the Official 60-Day Notice as she was not eligible for an Offer in Compromise (OIC) because of equity in non-exempt income and assets. After back and forth negotiations, the SBA Loan Specialist approved the Workout proposal, reducing the Client's purported liability by nearly $142,142.27 in accrued interest, and statutory collection fees. Without the Firm's intervention and subsequent approval of the Workout proposal, the Client's debt amount (with accrued interest, Treasury's statutory collection fee and Treasury's interest based on the Current Value of Funds Rate (CVFR) would have been nearly $291,030.
Clients obtained an SBA 7(a) loan for their small business in the amount of $298,000. They pledged their primary residence and personal guarantees as direct collateral for the loan. The business failed, the lender was paid the 7(a) guaranty money and the debt was assigned to the SBA. Clients received the Official 60-Day Notice giving them a couple of options to resolve the debt balance directly with the SBA before referral to Treasury's Bureau of Fiscal Service. The risk of referral to Treasury would add nearly $95,000 to the SBA principal loan balance. With the default interest rate at 7.5%, the amount of money to pay toward interest was projected at $198,600. Clients hired the Firm with only 4 days left to respond to the 60-Day due process notice. Because the clients were not eligible for an Offer in Compromise (OIC) due to the significant equity in their home and the SBA lien encumbering it, the Firm Attorneys proposed a Structured Workout to resolve the SBA debt. After back and forth negotiations, the SBA Loan Specialist assigned to the case approved the Workout terms which prevented potential foreclosure of their home, but also saved the clients approximately $294,000 over the agreed-upon Workout term with a waiver of all contractual and statutory administrative fees, collection costs, penalties, and interest.

The new Chapter 11 Subchapter V bankruptcy has many differences from a regular Chapter 11. For instance, some of the changes are as follows:
These changes will result in faster and thus less expensive reorganizations for small business.
The adequacy of an SBA OIC must begin with an evaluation of the assets of the obligor(s). The starting point is ordinarily the net present value of the forced sale value of such assets (not the loan balance). This value combined with the prognosis of the obligors’ earning power form the basis for determining the adequacy of the offer. The review must balance the right of the Government to collect the amount owed and the obligation to treat all obligors with dignity and fairness.
An SBA Loan Modification is a remedial option when the business is still a viable concern, is still generating revenue and due to current circumstances, the old loan terms just do not make financial sense for all parties. A loan modification package is generally presented when it involves a SBA 504 Loan and the collateral or building’s fair market value has decreased significantly such that the loan should probably be modified (i.e. principal and interest payment terms, modification of principal loan balance to reflect current fair market value appraisal of real estate collateral, payment schedule etc.). In this situation, special factors need to be evaluated, appraisals will need to be conducted, and a proposal should be made in order to apply for a loan modification which benefits both parties. Again, the borrower will be required to provide updated business and personal financial information, additional pledged collateral may be requested, and appraisals will be done as part of the modification process. This is not a situation where the borrower or guarantor should engage in this process without qualified representation or consultation. However, if the business feels that it doesn’t need assistance, we recommend that you review applicable SBA SOPs and the Code of Federal Regulations (CFRs) prior to presenting your loan modification application.
An SBA Loan Deferment is a temporary remedial option. If your business is having short term financial difficulty because of a seasonal slump and can reasonably prove through pro forma financial statements to your lender or CDC that a turnaround is around the corner and you need brief relief from paying on the SBA loan, you should consider applying for a deferment. Generally, if you qualify, your bank or CDC, with the SBA’s approval can provide you with either a six (6) month or twelve (12) month reprieve from paying either the principal amount (and allow interest-only payments) or no principal and interest. However, if you consider this option, be advised that you may be asked to reaffirm the loan with personal guarantees or even pledge additional collateral. Needless to say, this is not an option that you should consider without either representation or consultation with a qualified practitioner.
A charge off is justified when the SBA has complied with all requirements of collection and liquidation and further collection of any substantial portion of the debt is doubtful. The determination to justify a charge off may be based on one or more of the following:a) All efforts must have been exhausted in cost-effective recovery from:1. Voluntary payments from the borrower;2. Liquidation of collateral;3. Compromise with obligor leaving only a deficiency balance; and4. Consideration has been given to any legal remedies available so that no further reasonable expectation of recovery remains.b) Estimated costs of future collection exceed any anticipated recovery;c) Obligor cannot be located or is judgment proof;d) The Lender/SBA’s rights have expired (e.g., statute of limitations, restrictions of State law, SBA policy);e) Debt is legally without merit;f) Adjudication of a Chapter 7 Bankruptcy as a no asset case, or completion of Chap 11/13 case;g) The inability of the Lender to effect further worthwhile recovery.